
Financial literacy education is the systematic teaching of money management skills, covering everything from budgeting and saving to investing, debt management, and understanding credit. It equips people with the knowledge and confidence to make informed decisions about their personal finances throughout their lives.
For many Canadians, this education represents the difference between feeling overwhelmed by financial choices and taking control of their economic future. Despite handling money daily, most of us never receive formal training on how to manage it effectively. The consequences show up in troubling statistics: household debt levels that strain family budgets, inadequate retirement savings, and widespread confusion about basic financial products.
The need has never been more pressing. Housing costs continue climbing in major cities, the gig economy reshapes traditional employment, and Canadians face increasingly complex decisions about retirement planning, tax optimization, and investment strategies. Without a solid foundation in financial concepts, these challenges can feel insurmountable.
This article breaks down what financial literacy education actually entails, how it’s delivered in schools and communities, the core subjects it covers, and who benefits most from it. You’ll learn how these programs work in practice and discover whether financial education could fill gaps in your own knowledge or help family members build stronger money habits.
What Financial Literacy Education Means
Financial literacy education means learning how to understand, manage, and make informed decisions about money in everyday life. It’s the process of gaining knowledge and skills that help you navigate financial situations confidently, from paying bills and building savings to planning for retirement and avoiding costly mistakes.
Unlike the math classes you took in school, financial literacy education focuses on applying numbers to real-world money situations you’ll actually face. While general education might teach you how to calculate percentages, financial literacy shows you how to compare interest rates on loans, understand what compound growth means for your savings, or figure out whether leasing or buying makes more sense for your circumstances.
- Financial Literacy
- The ability to understand and use financial concepts like budgeting, investing, and credit to make sound money decisions.
- Financial Education
- The formal or informal process of learning financial concepts, skills, and strategies through courses, programs, or self-directed study.
- Financial Capability
- The combination of knowledge, skills, confidence, and access to resources needed to effectively manage money and act on financial decisions.
- Financial Wellness
- The state of having control over day-to-day finances, the capacity to absorb financial shocks, and the freedom to make choices that let you enjoy life.
The scope extends well beyond arithmetic. Financial literacy education includes understanding how financial systems work, recognizing the trade-offs in money decisions, knowing where to find trustworthy information, and developing habits that support long-term financial health. It covers practical topics like reading pay stubs, choosing insurance coverage, spotting predatory lending, and building an emergency fund, skills that directly affect your quality of life but rarely appear in traditional curricula.
How Financial Literacy Education Works
Where Canadians Learn Financial Skills
Canadians encounter financial literacy education through multiple channels, each offering distinct advantages depending on learning style, life stage, and accessibility needs.
The K-12 education system increasingly integrates money management lessons into curriculum, with provinces taking varied approaches to mandatory versus optional financial education courses. Post-secondary institutions often provide workshops and seminars for students navigating loans, credit, and independent finances for the first time.
Beyond formal education, Canadians access financial learning through:
- Community centres and public libraries hosting free workshops on budgeting, debt reduction, and saving strategies
- Workplace programs including lunch-and-learn sessions, retirement planning seminars, and employee financial wellness initiatives
- Credit counselling agencies offering one-on-one guidance and group education sessions
- Banks and credit unions providing resources, calculators, and educational materials both online and in-branch
- Non-profit organizations delivering targeted programs for specific demographics like newcomers, Indigenous communities, or low-income families
- Online platforms featuring courses, podcasts, videos, and interactive tools accessible anytime
- Government resources through agencies like the Financial Consumer Agency of Canada, offering guides and comparison tools
This diverse ecosystem means financial education isn’t confined to classrooms. Whether someone prefers structured courses, self-paced online learning, or personalized counselling, options exist across urban and rural communities. The variety of delivery methods helps reach Canadians where they are, removing traditional barriers to accessing financial knowledge.
Teaching Methods That Build Money Skills
Financial literacy sticks when learners actively engage with money concepts rather than passively absorbing information. The most effective teaching methods move beyond lectures and textbooks to create experiences that mirror real financial decisions.
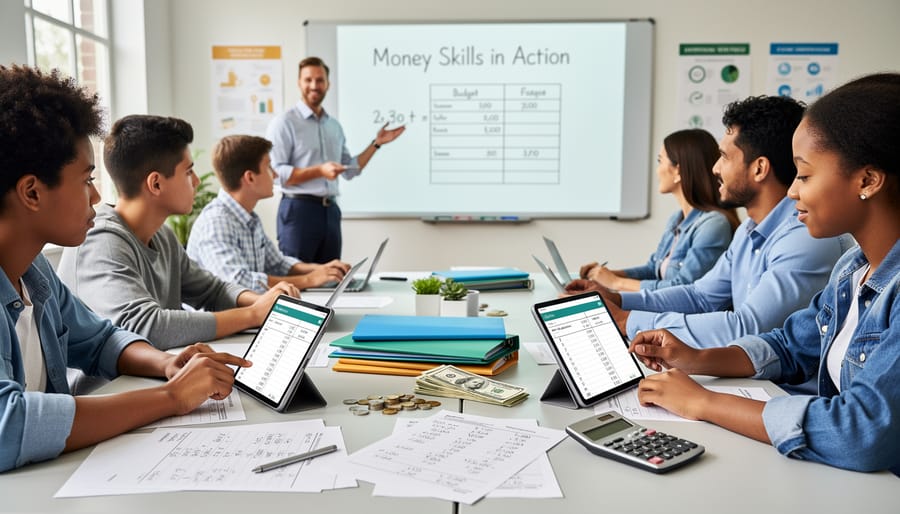
Interactive workshops lead with practical scenarios: participants might work through sample budgets based on actual income levels, debate spending priorities in small groups, or role-play salary negotiations. This collaborative approach helps people test their assumptions and learn from peers facing similar financial challenges.
Simulation exercises create safe spaces to practice without real-world consequences. Digital budgeting simulators let learners experience the cascading effects of financial choices over months or years in minutes. Stock market simulations teach investment principles through virtual portfolios. Even simple paper-based exercises where participants allocate a mock paycheck across competing needs build decision-making skills that transfer to real life.
Case studies ground abstract concepts in reality. Examining how real families recovered from debt, built emergency funds, or saved for major purchases makes strategies tangible and relatable. These stories provide mental models learners can adapt to their own circumstances.
Mentorship programs pair experienced money managers with those building skills, offering personalized guidance that addresses individual financial situations. A mentor can answer specific questions, provide accountability, and help learners navigate decisions as they arise.
Digital learning tools, from budgeting apps to educational videos, accommodate different learning styles and schedules. The flexibility of online resources means Canadians can build financial skills at their own pace, revisiting concepts as needed and applying lessons immediately to their personal finances.
Core Components of Financial Literacy Programs
Effective financial literacy programs share a common blueprint, covering seven interconnected subject areas that together build complete money management capability.
Budgeting and cash flow management forms the foundation. This teaches tracking income and expenses, creating realistic spending plans, and understanding where money actually goes each month. Without mastering cash flow, the other components remain theoretical.
Saving and investing builds on budgeting by showing how to set aside money systematically and make it grow. Programs cover emergency funds, goal-based savings, investment vehicles like TFSAs and RRSPs, and basic principles of risk and return. The emphasis shifts from preserving money to building wealth over time.
Debt management addresses borrowing responsibly, understanding interest rates, prioritizing repayments, and recognizing when debt becomes problematic. This component connects directly to cash flow management, as debt obligations reshape monthly budgets and long-term financial plans.
Credit understanding explains how credit scores work, what lenders look for, and how borrowing decisions made today affect future opportunities. Strong credit and cost traps awareness helps Canadians avoid expensive mistakes when applying for mortgages, car loans, or lines of credit.
Insurance and risk management introduces protection strategies, covering home, auto, life, and disability insurance. This component often gets overlooked in informal financial education, yet proper coverage protects everything else you’ve built.
Tax basics demystify filing requirements, common deductions, tax-advantaged accounts, and year-end planning strategies. Understanding taxes helps Canadians keep more of what they earn and make smarter decisions about income, investments, and timing.
Retirement planning ties the previous elements together, projecting future needs and creating strategies to meet them. Programs explore CPP, OAS, employer pensions, personal savings, and withdrawal strategies.
These components don’t exist in isolation. Strong national financial literacy initiatives recognize that debt management affects credit scores, which influence insurance rates, while tax strategies shape retirement planning. Comprehensive programs weave these subjects together, showing how daily budgeting decisions compound into long-term financial security.
Who Benefits from Financial Education
Financial literacy education isn’t reserved for one age group or income bracket, it creates measurable advantages for Canadians at every life stage and economic level.
Young people gain the most from early exposure. Students who learn budgeting, saving, and credit fundamentals before entering the workforce make fewer costly mistakes with their first paycheques, student loans, and credit cards. High school and post-secondary programs that teach practical money management give graduates a head start that compounds over decades, helping them avoid debt traps and build wealth earlier.
Young adults navigating major financial milestones, first apartments, car purchases, marriage, homeownership, benefit from education that demystifies mortgages, insurance, and investment accounts. Without this knowledge, they’re vulnerable to predatory lending, unnecessary fees, and missed opportunities for tax-advantaged saving. Even basic understanding of how interest works or what an RRSP does can alter financial trajectories.
Families managing household budgets find financial education helps them stretch income further, plan for children’s education, and weather unexpected expenses without spiralling into debt. Parents who understand cash flow and emergency funds create more stable homes and model healthy money habits for their kids, building money skills across generations.
Entrepreneurs and small business owners need financial literacy to separate personal and business finances, manage cash flow, understand profit margins, and make smart growth decisions. Many businesses fail not from bad products but from poor financial management, education directly reduces that risk.
Seniors benefit by learning to manage fixed incomes, understand government benefits, avoid financial scams targeting older adults, and make informed decisions about estate planning and healthcare costs. It’s never too late to improve financial security.
The common thread: financial education meets people where they are, addressing real challenges they face right now while building capability for future decisions.
Real-World Applications of Financial Literacy
Financial literacy education changes how people handle their daily money decisions and shapes their long-term financial stability. When you understand basic concepts like compound interest, debt-to-income ratios, and diversification, you stop making choices based on guesswork or emotional impulses and start making informed decisions backed by knowledge.
Someone who has learned about credit utilization knows that maxing out a credit card damages their score even if they pay on time, so they keep balances below 30% of their limit. A person educated about mortgage structures understands why a slightly higher interest rate with prepayment flexibility might beat a locked-in lower rate for their situation, they grasp the financial words every homeowner needs to negotiate confidently.
The impact shows up in specific, measurable ways:
- Choosing appropriate insurance coverage instead of being over-insured or dangerously underprotected
- Recognizing investment scams and high-fee products that erode returns over decades
- Negotiating better rates on loans, mortgages, and service contracts
- Building emergency funds that prevent debt spirals when unexpected expenses hit
- Starting retirement savings early enough for compound growth to work effectively
Financially literate Canadians read the fine print on contracts, compare total borrowing costs rather than just monthly payments, and understand the tax implications of different account types. They know when to seek professional advice and which questions to ask, turning financial advisors into collaborators rather than mysterious authorities.
This education doesn’t guarantee wealth, but it consistently reduces costly mistakes. Research shows people with stronger financial knowledge pay lower interest rates, accumulate more savings, and experience less financial stress regardless of income level. The knowledge becomes a filter for every money decision, large and small.
Common Questions About Financial Literacy Education
Canadians approaching financial education for the first time often have similar concerns and questions. Here are straightforward answers to help you get started with confidence.
Is it too late to start learning about money management?
It’s never too late to improve your financial literacy. Adults of any age can benefit from learning new money management strategies, and even small improvements in financial knowledge lead to better decision-making regardless of when you start.
Where can I find trustworthy financial education resources?
Look for resources from established Canadian organizations like the Financial Consumer Agency of Canada, provincial securities commissions, credit unions, and non-profit consumer advocacy groups. Avoid sources trying to sell you specific financial products while claiming to educate you.
How long does it take to see real results from financial education?
Many people notice immediate benefits from applying basic budgeting and tracking strategies within the first month. More complex goals like debt reduction or building savings show measurable progress within three to six months of consistent application.
Do I need a background in math or finance to understand financial literacy?
No specialized background is required. Financial literacy education starts with basic concepts and uses everyday math that most adults already know. The focus is on practical application, not complex calculations.
The effectiveness of financial education depends largely on how you apply what you learn. Reading about budgeting helps, but creating and following an actual budget creates change. Start with one area that matters most to your current situation, whether that’s reducing debt, building an emergency fund, or understanding your pension options. Progress builds confidence, which encourages you to tackle more complex financial topics over time.
Don’t expect perfection or wait until you feel completely prepared. Financial literacy grows through practice and real-world experience, not just study.
Financial literacy education isn’t some elite skill reserved for finance professionals, it’s a practical, learnable toolkit that any Canadian can use to take control of their money. Whether you start with a free online course, ask questions at your bank, or simply begin tracking your spending, each small step builds the foundation for smarter financial decisions.
The beauty of financial education is that you don’t need to master everything at once. Understanding how credit cards actually work improves your borrowing decisions. Learning basic budgeting principles helps you identify where your money goes each month. Grasping the fundamentals of investing opens doors to long-term wealth building. These aren’t abstract concepts, they’re skills that directly impact your day-to-day financial security and future planning.
Think of financial literacy as an ongoing journey rather than a destination you reach and forget. Your financial needs evolve as you move through life stages, from managing student debt to planning retirement. Staying curious and continuing to learn ensures you’re equipped to handle whatever financial challenges or opportunities come your way. The knowledge you build today shapes the financial stability you’ll enjoy tomorrow.