
National financial literacy is the collective capacity of a country’s population to understand and effectively manage money, from everyday budgeting and saving to investing, debt management, and retirement planning. When Canadians lack these skills, the consequences ripple through entire communities: households struggle with mounting debt, families postpone major life decisions, and economic resilience weakens across generations.
The stakes are personal and national. Without a strong foundation in financial concepts, people find themselves vulnerable to predatory lending, unable to build emergency savings, or unprepared for retirement. Communities with lower financial literacy rates often experience higher rates of bankruptcy and financial stress, creating pressure on social services and limiting economic mobility.
Canada has recognized this challenge and responded with targeted initiatives. The Financial Consumer Agency of Canada coordinates national efforts, working with provinces, schools, employers, and community organizations to embed financial education into daily life. Programs range from classroom curricula teaching high school students about credit and compound interest, to workplace pension education, to free online tools helping families create realistic budgets.
But progress remains uneven. Access to quality financial education varies significantly by region, income level, and age group. Many Canadians still learn money management through trial and error rather than structured instruction. Rural communities often have fewer resources than urban centres, and newcomers to Canada may navigate an unfamiliar financial system without adequate support.
The path forward requires sustained commitment. Building national financial literacy means meeting people where they are, whether that’s a community centre workshop, a university seminar, or a smartphone app, and providing practical knowledge they can use immediately.
What National Financial Literacy Means
National financial literacy represents the collective capacity of a country’s population to understand and manage money effectively. It extends beyond basic arithmetic or knowing how to balance a chequebook. At its core, it encompasses the skills needed to budget household income, save for both short-term goals and emergencies, invest wisely for the future, manage debt responsibly, and plan for a secure retirement. When these capabilities are widespread across a society, individuals make sounder financial decisions, households experience less economic stress, and communities build greater resilience against financial shocks.
What distinguishes national financial literacy from individual financial education is scale and approach. While personal financial education focuses on one person learning to improve their own money management, national financial literacy involves coordinated, large-scale initiatives led by governments, educational institutions, and community organizations. These efforts aim to embed financial knowledge into the fabric of society, ensuring that every Canadian, regardless of where they live, their income level, or their background, has access to the tools and information needed to navigate financial decisions confidently.
This systemic approach recognizes that financial capability isn’t just a personal responsibility. It’s a shared societal goal that requires schools to teach money skills early, employers to support financial wellness, and public agencies to provide accessible resources. The emphasis is on reaching everyone, from students just starting to understand earning and spending, to older Canadians planning their retirement years.
Why National Financial Literacy Matters for Canadians
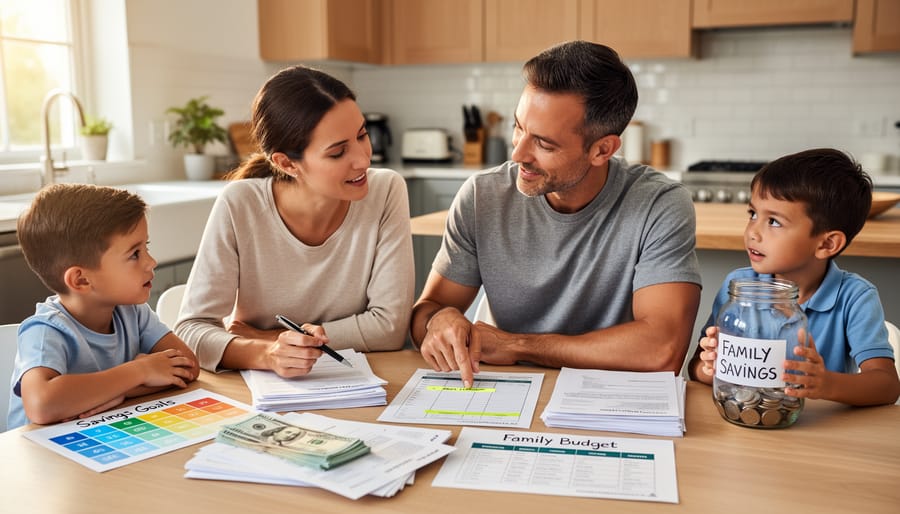
When Canadians struggle with money decisions, the ripple effects touch every corner of their lives, delayed retirements, mounting credit card balances, sleepless nights over mortgage payments, and difficult conversations around the kitchen table. National financial literacy matters because it addresses these challenges at scale, equipping people across the country with the tools to build stability and confidence in their financial futures.
Strong financial literacy helps households make informed choices about major commitments. Understanding homeowner financial words like amortization, equity, and debt service ratios empowers buyers to negotiate better mortgage terms and avoid costly mistakes. Similarly, budgeting for home repairs becomes less overwhelming when families know how to plan for maintenance costs and distinguish between needs and wants.
Beyond homeownership, financial literacy reduces debt stress by teaching Canadians how to evaluate credit products, recognize predatory lending, and develop repayment strategies that fit their income. It shifts the mindset from managing crises to preventing them.
Retirement planning represents another critical area where knowledge gaps create vulnerability. Many Canadians underestimate how much they’ll need or misunderstand how registered accounts work, leaving them underprepared for later years. When more people grasp the basics of compound growth, employer matching, and tax-advantaged saving, they’re better positioned to secure their futures without excessive reliance on government programs.
At a broader level, financially literate populations contribute to economic resilience. They weather downturns more effectively, make sounder investments, and participate more confidently in markets. This reduces strain on social safety nets and creates communities where people can focus on building rather than merely surviving.
The Canadian context adds unique considerations, variable housing costs across provinces, diverse immigrant communities with different financial backgrounds, and evolving retirement landscapes. Addressing these through coordinated national efforts ensures no one gets left behind simply because they didn’t learn money management in school or at home.
Key Components of Effective National Financial Literacy Programs
Education System Integration
Embedding financial literacy into school curricula gives students practical money skills early, when habits form and compound over time. In Canada, provinces set their own education standards, leading to varied approaches. Some have integrated budgeting, saving, and credit concepts into math or social studies classes, while others offer standalone personal finance courses at the high school level.
The goal is to graduate students who can read a pay stub, open a bank account, compare loan terms, and start building credit responsibly, tasks they’ll face soon after leaving school. At the post-secondary level, colleges and universities increasingly offer workshops on managing student loans, understanding debt, and planning for life after graduation.
Challenges remain. Not all teachers receive training in financial topics, and curriculum space is limited. Yet the payoff is clear: young adults who learn these skills in school tend to make more informed choices about borrowing, saving, and investing as they enter the workforce. Strengthening this foundation across all provinces helps ensure that financial literacy becomes a universal starting point rather than a privilege.
Community and Workplace Initiatives
Local organizations, employers, and non-profits play a vital role in extending financial literacy beyond the classroom, reaching Canadians where they live and work. Community centres, libraries, and settlement agencies often host free workshops covering everyday money topics, budgeting basics, understanding credit scores, navigating tax season, and avoiding predatory lending. These sessions meet people where they are, offering practical guidance in familiar settings and sometimes in multiple languages to serve diverse populations.
Employers increasingly recognize that financially stressed employees are less productive and more likely to leave. Many now offer workplace financial wellness programs, ranging from lunch-and-learn seminars on retirement planning to one-on-one coaching sessions with financial advisors. Some provide access to digital tools that help staff track spending, set savings goals, or model debt repayment strategies. On-the-job programs work because they’re convenient, confidential, and tailored to the specific benefits and compensation structures employees already have.
Non-profit organizations, including credit counselling agencies, housing advocates, and youth-serving groups, fill gaps by targeting populations who face unique financial challenges. Newcomers may need guidance on building credit history in Canada, while low-income families benefit from programs linking financial education to matched savings accounts or asset-building incentives. Together, these community and workplace efforts create a layered support system that complements formal education and government initiatives, ensuring financial literacy reaches Canadians at every stage of life.
How Canada Approaches Financial Literacy
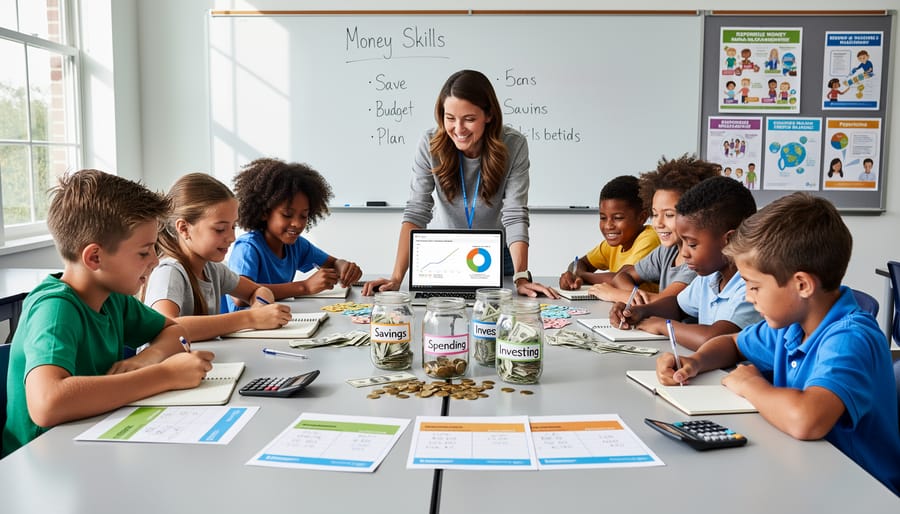
Canada’s approach to financial literacy operates through a multi-layered framework that brings together federal leadership, provincial programs, and community partnerships. At the national level, the Financial Consumer Agency of Canada (FCAC) serves as the primary coordinator, developing strategies and resources to improve money management skills across the country. The agency works to ensure Canadians have access to reliable information about budgeting, credit, investing, and financial planning through various channels.
Provincial governments complement federal efforts with their own initiatives tailored to regional needs. Some provinces have integrated financial education into school curricula, while others focus on adult learning programs through libraries, community centres, and vocational training facilities. This decentralized approach allows regions to address specific economic challenges their residents face, whether that’s managing housing costs in urban centres or planning for seasonal employment in resource-based communities.
Financial institutions play a significant role by offering free workshops, online tools, and educational materials to customers and the broader public. Banks and credit unions often partner with schools and community organizations to deliver seminars on topics ranging from opening a first bank account to building savings for renovations or retirement. These partnerships extend reach beyond what government programs alone can achieve.
Non-profit organizations contribute valuable expertise as well, particularly in serving newcomers, seniors, and other groups that may face barriers to accessing mainstream financial services. Community groups deliver workshops in multiple languages and culturally relevant contexts, helping immigrants understand the Canadian financial system and how it differs from their countries of origin.
The collaborative model Canada has developed recognizes that no single entity can address financial literacy in isolation. Federal guidance sets direction, provinces adapt implementation, institutions provide practical tools, and community groups ensure inclusivity, creating a network designed to meet Canadians where they are and support their financial capability development.
Challenges and Opportunities Ahead
Building financial literacy nationwide requires overcoming real obstacles while seizing new ways to reach Canadians where they are.
Accessibility remains a fundamental challenge. Rural and remote communities often lack in-person financial education resources that urban centres take for granted. Indigenous communities face additional barriers, including historical exclusion from mainstream financial systems and a shortage of culturally relevant programming. Language diversity adds another layer of complexity, newcomers to Canada need financial education that accounts for different banking systems, unfamiliar mortgage and credit terms and cultural perspectives on money management.
The digital divide cuts both ways. While technology opens doors for online learning modules and financial apps, it excludes those without reliable internet access or digital skills. Older Canadians who didn’t grow up with smartphones may struggle to access resources designed for mobile-first delivery. Meanwhile, younger generations comfortable with technology can still lack critical knowledge if programs aren’t engaging or relevant to their financial situations.
Age-specific engagement gaps persist across the spectrum. School-age children receive inconsistent financial education depending on provincial curriculum choices. Young adults juggling student debt and first jobs often deprioritize learning. Mid-career Canadians feel too busy, while retirees may believe it’s too late to change habits.
Yet opportunities are expanding. Technology enables scalable, low-cost education through videos, podcasts, and interactive tools that meet people in their daily routines. Public awareness is growing as financial stress becomes a more open conversation. Cross-sector partnerships between governments, financial institutions, employers, and community organizations are creating more touchpoints for education. The challenge now is ensuring these opportunities translate into meaningful, lasting improvements in financial capability for all Canadians.
Common Questions About National Financial Literacy
Who provides financial literacy education in Canada?
Financial literacy education comes from multiple sources, including federal agencies like the Financial Consumer Agency of Canada, provincial programs, school boards, non-profit organizations, credit unions, banks, and community centres. Many employers also offer workplace financial wellness programs as part of their benefits packages.
Are financial literacy programs free to access?
Most government-supported and non-profit financial literacy programs are free, including online resources, workshops, and educational materials from agencies like FCAC. Some private sector offerings may charge fees, but a wealth of quality information and tools are available at no cost to Canadians.
How can I find financial literacy resources in my area?
Start with the Financial Consumer Agency of Canada’s website, which lists programs and tools across the country. Check with your local library, community centre, or credit union for in-person workshops. Provincial governments often maintain directories of approved financial education providers in your region.
What can I do to improve my own financial knowledge?
Begin with the basics: review your budget, track spending for a month, and set one specific financial goal. Explore free online courses, read personal finance books from Canadian authors, and consider working through modules on topics like debt management or retirement planning at your own pace.
Beyond formal programs, building financial literacy is an ongoing personal commitment. Start small by dedicating time each week to learning one new concept, whether it’s understanding how credit scores work, exploring different investment options, or reviewing insurance coverage. The key is consistency rather than trying to master everything at once.
Many Canadians find success by combining self-directed learning with occasional professional guidance. You might work through online resources independently but consult a fee-only financial planner for specific questions about your situation. This hybrid approach helps you build knowledge while getting expert input on complex decisions like mortgage selection or retirement strategy.
Remember that financial literacy isn’t just about accumulating information, it’s about applying what you learn to your daily choices. Put new concepts into practice immediately, even in small ways. Understanding compound interest becomes more meaningful when you actually open a savings account and watch it grow. Learning about diversification makes more sense once you review your own investment mix.
National financial literacy stands as more than just an educational initiative, it’s a critical foundation for individual well-being and collective economic resilience. When Canadians of all ages and backgrounds understand how to budget, save, manage debt, and plan for the future, households become more stable and communities grow stronger.
The work doesn’t stop with a single program or awareness campaign. Building true financial capability requires sustained effort across every layer of society. Schools must equip students with money skills before they face real-world financial decisions. Employers can support their teams through workplace education. Community centres and libraries serve as trusted local hubs where people can access guidance without judgment. Financial institutions and government agencies each play a role in making resources accessible and relevant.
Progress happens when these efforts connect and reinforce one another, creating pathways for Canadians to learn at every stage of life.
If you’re looking to strengthen your own financial knowledge, start by exploring what’s available in your province or community. Many resources are free, practical, and designed with real-life situations in mind. Taking that first step, whether it’s attending a workshop, reading a guide, or simply asking questions, can open doors to greater confidence and control over your financial future.